Pricing your home right in Central NJ means anchoring to hyper-local comps, not county averages. With Middlesex County inventory rising and 13% of listings taking price cuts, homes priced accurately
Dated: May 25 2026
Views: 115
Nearly half of Veterans (49%) feel homeownership is currently out of reach, according to a recent survey from NewDay USA.
But many are closer than they think. And you might be, too.
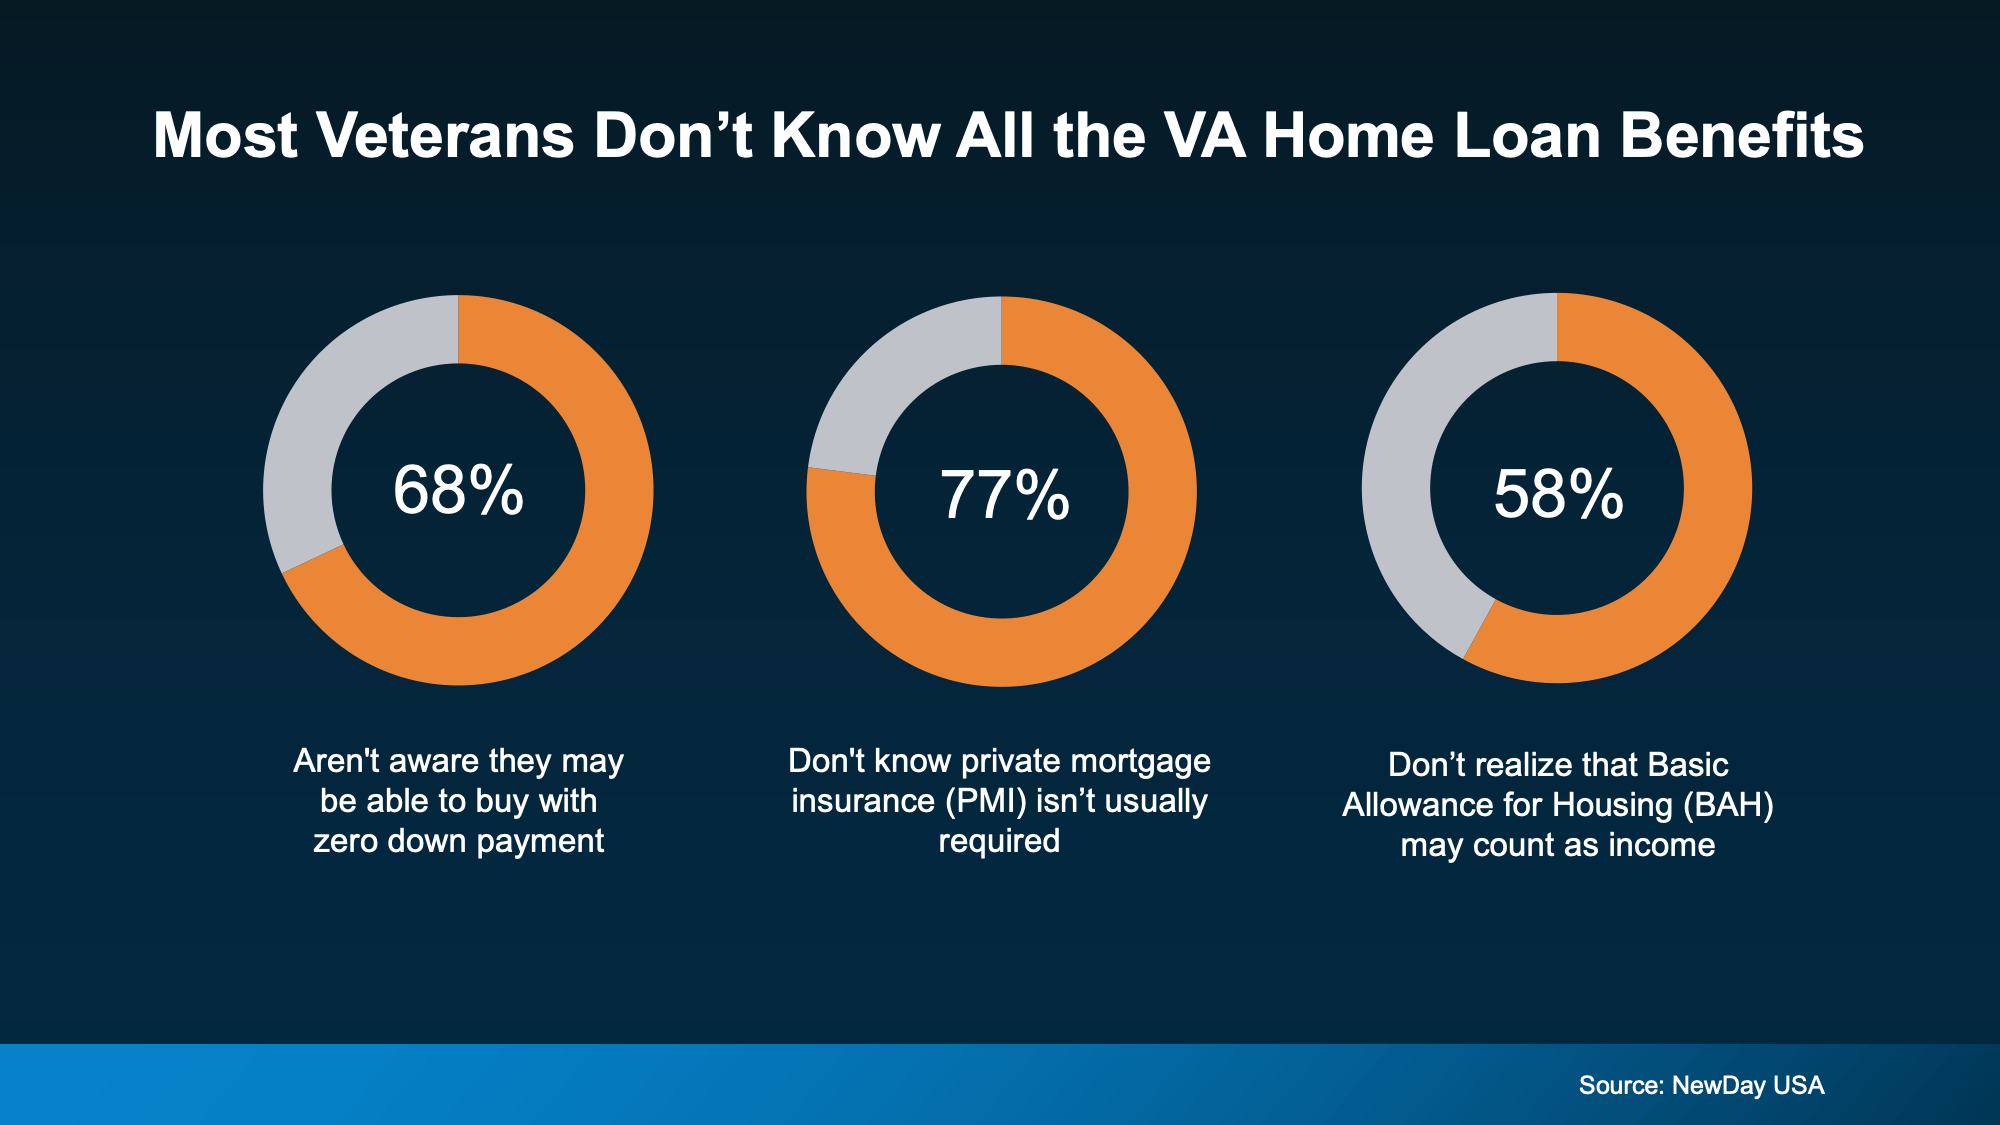
If you’re a Veteran, you probably know the Veterans Affairs (VA) home loan benefit exists – it's been around for over 80 years. What you might not know is what it actually covers. Three misconceptions trip up Veterans the most (see graph below):
 Any one of those beliefs could be holding you back. Let’s walk through all three, so you have the information you really need.
The potential to put zero money down is probably the biggest perk of a VA loan, but most homebuyers don’t even realize that’s an option. According to the NewDay USA survey, many respondents guessed they’d need to save somewhere between $10,000 and $19,900 before they could buy. That’s years of saving for an upfront cost that isn’t always required.
According to the Department of Veterans Affairs, with VA loans, there can be limits on the types of closing costs buyers have to pay. That means more money stays in your pocket on closing day – and you have less to save up for before you can buy. The benefit combined with the down payment perk can speed up your buying timeline.
Unlike many other loan options, VA loans typically don’t require private mortgage insurance (PMI), even with low or no money down. If you take out a conventional loan instead, you could pay $100 to $300 a month in PMI until you hit 20% equity, according to NewDay USA. Over time, that’s a difference of thousands of dollars.
If you’re on active duty or if you’re a qualifying reservist, your Basic Allowance for Housing (BAH) and Basic Allowance for Subsistence (BAS) may count toward income qualification on a VA loan. So, if you were running the numbers without factoring your BAH or BAS in, you could qualify for more than you thought. Both BAH and BAS are non-taxable, so they can help raise the amount you can qualify for.
VA home loans can put homeownership within reach, and a trusted lender can help make sure you understand the details before you move forward.
If you’re active duty, you’ve served, or know someone who has, connect with a trusted lender who can walk you through whether you’d qualify and what the VA benefit offers. You may be able to buy a home sooner than you thought.
Meet Your Trusted Local Real Estate Expert! Embark on your property journey with a seasoned real estate professional, passionately serving clients across Middlesex, Somerset, and Union counties, NJ. ....
Pricing your home right in Central NJ means anchoring to hyper-local comps, not county averages. With Middlesex County inventory rising and 13% of listings taking price cuts, homes priced accurately
In Central NJ's more competitive 2026 market, the fixes that move the needle are targeted and cost-effective: fresh neutral paint, curb appeal basics, minor kitchen and bath refreshes, and
Selling your house this fall is absolutely doable. But there’s something you need to know about this time of year. Buyer activity typically starts to slow while the number of homes for
A smooth military relocation to Central New Jersey starts with contacting Joint Base McGuire-Dix-Lakehurst's housing office as soon as your orders arrive, understanding your on-base and off-base
 The data relating to real estate for sale on this website comes in part from the IDX Program of Garden State Multiple Listing Service, L.L.C. and Elite. Real estate listings held by other brokerage firms are marked as IDX listing. Information deemed reliable but not guaranteed. Copyright © 2026 Garden State Multiple Listing Service, L.L.C. All rights reserved. This information is being provided for Consumer's personal, non-commercial use and may not be used for any purpose other than to identify
prospective properties Consumers may be interested in purchasing
The dissemination of listings on the website does not constitute the consent required by N.J.A.C. 11.5.6.1 (n) for the advertisement of listings exclusively for sale by another broker. Any such consent must be obtained in writing from the listing broker.
Show More...
 The data relating to real estate for sale on this web-site comes in part from the Internet Listing Display database of the ALL JERSEY MULTIPLE LISTING SYSTEM, INC. Real estate listings held by brokerage firms other than this site-owner are marked with the ILD logo. The ALL JERSEY MULTIPLE LISTING SYSTEM, INC. does not warrant the accuracy, quality, reliability, suitability, completeness, usefulness or effectiveness of any information provided.
The information being provided is for consumers' personal,
non-commercial use and may not be used for any purpose other than to identify properties the consumer may be interested in purchasing or renting.
Copyright 2026, ALL JERSEY MULTIPLE LISTING SYSTEM, INC. All rights reserved. The ALL JERSEY MULTIPLE LISTING SYSTEM, INC retains all rights, title and interest in and to its trademarks, service marks and copyrighted material.
Show More...
 All information is believed to be accurate but is not guaranteed. Protected by Copyright© 2026 and is owned either by the Monmouth County Association of REALTORS; or by the developers of the software, Kunversion, LLC. All rights reserved. Each office independently owned and operated.
The New Jersey Real Estate Commission requires every licensed broker or salesperson with whom you list your property to give you a copy of this notice. The purpose is to help you comply with the New Jersey Law
Against Discrimination (the "LAD) and federal laws prohibiting discrimination in the sale or rental of real property.
In New Jersey, it is illegal to discriminate against a prospective or current buyer or tenant because of race, creed, color, national origin, sex, gender identity or expression, marital status, civil union status, or source of lawful income used for mortgage or rental payments. It is also illegal to place any advertisement or make any statements or utterances that express, directly or indirectly, any limitations to offer housing based on any of those characteristics.
Show More...
